China NFC Solutions for Seamless Contactless Transactions
2026-10-21
As contactless payments become the norm across the globe, China is leading the charge with advanced NFC solutions that make transactions smoother than ever. From subway turnstiles to street vendors, the tap-and-go experience is now second nature for millions—but what makes it all work seamlessly? OSRFID is at the heart of this evolution, providing the reliable NFC technology that keeps China’s digital economy moving at full speed. In this post, we’ll explore how these solutions are transforming everyday commerce and why they matter for the future of payments.
Tapping Into Daily Life: The Quiet Spread of Contactless Payments
The shift didn't arrive with a bang. It slipped in through the side door of daily routine—on the bus, at the corner bakery, in the line for a morning coffee. A quick tap of a card or phone against a reader, a soft beep, and the transaction is done before most people even register it. Contactless payments have stopped being a novelty and started behaving like background noise: always there, rarely noticed, but quietly reshaping how money moves.
What makes this spread so unassuming is its lack of friction. Small vendors who once had a two-dollar minimum for cards now wave customers through with a tap, no signature or PIN required for modest amounts. The old rituals—digging for change, waiting for chip insertion, signing a receipt—are fading without anyone declaring them obsolete. Even the most routine purchases, from a parking meter to a farmers' market stall, now feel less like transactions and more like brief interruptions in an otherwise continuous day.
Perhaps that's the real story: not that contactless payments won, but that they won by becoming forgettable. The technology doesn't ask for attention; it simply works and gets out of the way. As more people leave physical wallets behind in favor of a phone or a slim cardholder, the very idea of "paying" is being compressed into a half-second gesture. The result isn't a revolution you read about—it's a habit you already have.
The Infrastructure Bet That Made Every Terminal Smart
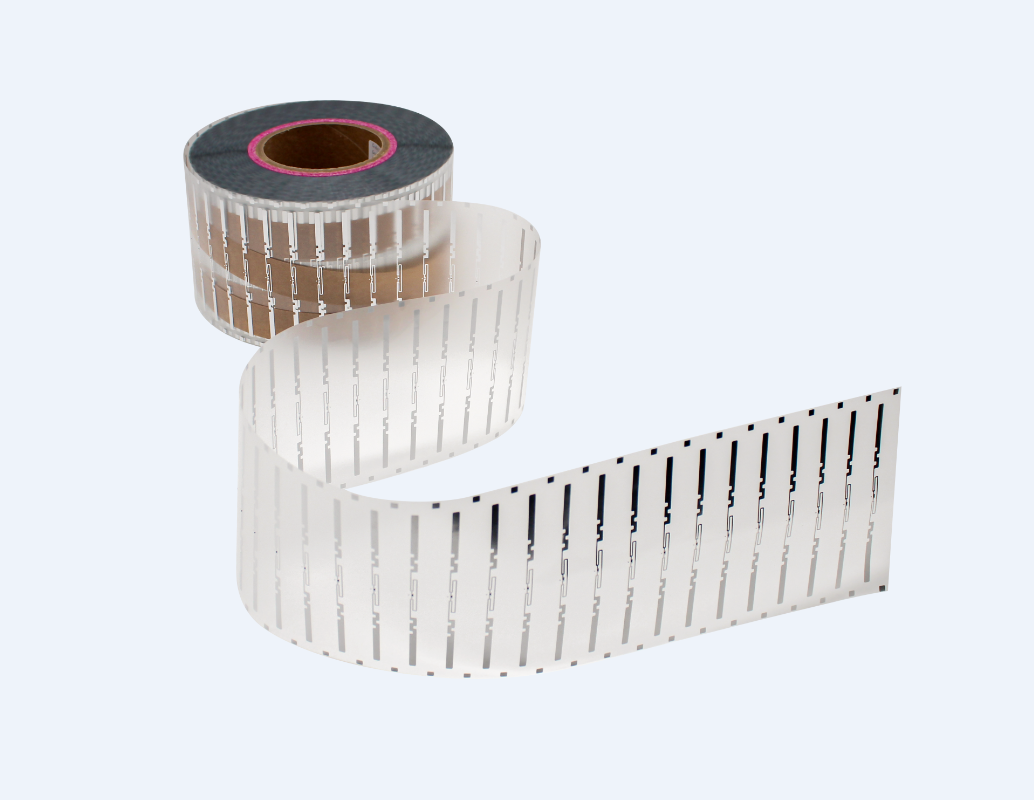
The shift did not begin with a flashy device launch or a marketing campaign. It started in the unglamorous layer most users never see: the bootloader, the local cache, the fallback network stack. Before any terminal could handle a payment or display a boarding pass without a stable connection, someone had to decide that every endpoint would carry enough compute power and local intelligence to keep working when the network blinked. That decision meant redesigning the entire hardware line around a small but capable processor, bundling a lightweight runtime, and accepting higher per-unit costs for years before the market caught up.
What made the bet unusual was its invisibility. The team did not sell consumers a smarter screen. They sold terminal manufacturers a set of shared building blocks: a secure enclave for keys, a deterministic update mechanism, and a set of APIs that treated offline as the default state rather than a failure to be handled later. Once those pieces were in place, every new terminal inherited the same baseline. A barcode scanner in a warehouse became capable of queueing scans locally and syncing them in bursts. A payment pad at a fuel pump could continue authorizing transactions with stored risk rules when the wide-area link dropped.
In hindsight, the infrastructure looks obvious. Of course a terminal should not freeze because a cable was unplugged. Of course updates should roll out without a technician visiting each site. But at the time, the dominant logic favored cheap dummy endpoints and centralized control. The bet succeeded because it treated local intelligence not as a feature to be added later, but as the foundation that every other capability would rely on. That quiet architectural choice changed what a terminal was allowed to be.
One Phone, No Wallet: How NFC Became the Default in China
Standing at a subway turnstile in Shanghai, you'll see commuters swipe their phones without breaking stride. What used to require fishing out a transit card or counting coins now happens in the time it takes to blink. NFC didn't win by being flashy; it won by becoming invisible. The phone replaced the card, then the card replaced the cash, until the whole idea of a separate wallet felt like carrying a second pair of keys.
The real turning point came when transit systems, convenience stores, and even small breakfast stalls started accepting contactless payments through the same chip already used for door access and ID verification. No one had to learn a new behavior—just tap the thing already in your hand. Once that habit formed, the wallet didn't stand a chance.
From Turnstiles to Taxis: The Transit-First Contactless Revolution
The contactless habit did not begin with coffee or groceries. It was built underground, at the turnstile. Commuters in cities like London and Tokyo tapped transit cards long before bank cards went contactless. That daily, high-frequency, low-friction tap trained millions to expect speed without reaching for a wallet.
Once that muscle memory formed, it jumped from the subway to the street. Taxis, ride-shares, and even bike rentals accepted the same simple tap. Drivers no longer fumbled with cash, and passengers did not wait through chip-and-PIN prompts. The fare became a background event rather than a moment of friction.
This transit-first wave rewrote payment behavior. It proved that removing friction in the most rushed, repetitive environment pushes people to carry that habit everywhere else. The turnstile was the gateway; the taxi was just the next tap.
Trust at the Speed of Tap: Security Without the Friction
Tap-to-pay and one-touch login have quietly rewritten the rules of digital trust. Gone are the days when verifying your identity meant typing a sixteen-character password, waiting for a text code, and hoping the session didn't time out. Now, a fingerprint on a sensor or a quick glance at your phone is enough to approve a purchase or unlock an account. The security is still there—layered under the hood—but it no longer demands your attention. That's the real breakthrough: protection that moves at the pace of a tap, without making you think about it.
What makes this work is not just faster hardware but a shift in how we design for trust. Instead of adding steps to prove you're you, modern systems verify continuously in the background, using device signals, behavioral patterns, and encrypted biometrics. A payment goes through in milliseconds because the risk engine has already done its job. The friction we used to accept as the price of safety has turned out to be unnecessary. And once users experience that seamless blend of speed and security, they rarely want to go back.
The Next Wave: NFC Beyond Transactions in Chinese Cities
Walk through any subway gate in Shanghai or unlock a shared bike in Chengdu, and you'll notice something curious: the phone rarely leaves the pocket. What started as a tap-to-pay convenience has quietly thickened into an invisible layer of urban life. Near Field Communication is no longer just about clearing a checkout line—it's becoming the quiet skeleton key for movement, identity, and access across Chinese cities, often without a single yuan changing hands.
Consider the typical weekday in Shenzhen. You tap your wristband to enter the office tower, swipe the same device at the gym locker, then use it to borrow a power bank at the mall. None of these moments feel like a transaction; they feel like the building recognizing you. This shift from payment to presence is reshaping how residents think about credentials. Instead of fumbling for a keycard or scanning a QR code, the NFC chip acts as a low-energy handshake—confirming who you are, where you're allowed to go, and what you've already reserved, all in under half a second.
The real differentiator, though, is how Chinese cities have folded NFC into broader platform ecosystems. In Hangzhou, a single tap at a community gate logs your entry into the property management app, which might simultaneously notify a delivery locker to release a package. Public libraries in Guangzhou let members check out books by grazing a phone against the shelf tag, while some residential compounds link NFC tags to visitor pre-registration, so a courier can enter without calling up. Because these functions are stitched into super-apps rather than standalone passes, the technology feels less like a feature and more like the city quietly remembering you. That ambient familiarity—not a flashy new gadget—is where the next wave of NFC is actually breaking.
FAQ
China NFC solutions combine hardware like POS terminals with mobile wallet apps such as Alipay and WeChat Pay. They work by letting a phone or card communicate with a reader over short distances, so a payment completes in under a second without physical contact.
Public transit, convenience stores, supermarkets, and vending machines are heavy users. Many subway systems in cities like Shanghai and Shenzhen accept NFC-based transit cards or phone wallets, while small merchants often have NFC-enabled QR hybrid terminals.
They use tokenization and encryption similar to global EMV standards, so the actual card number is never transmitted. The risk is low because each transaction generates a unique code, and the short read range makes eavesdropping difficult.
China blends NFC with QR code payments, so consumers can choose either method at the same terminal. The infrastructure is also heavily integrated with super apps, meaning a single phone wallet can handle transit, in-store purchases, and peer-to-peer transfers.
It depends on the app and merchant. Many large retailers and hotels accept international NFC wallets like Apple Pay or Google Pay, but smaller vendors often only support local QR platforms. Some Chinese banks now issue tourist-friendly prepaid cards that work with NFC terminals.
Brands like Xiaomi, Huawei, and Oppo embed NFC chips in most mid-range and flagship phones. They also pre-install wallet apps that support transit cards, access cards, and payments, which pushes NFC usage beyond just credit cards.
Some transit cards and wearable devices store value directly on the chip, so they work without a network connection. For phone-based NFC payments, a short offline window is allowed through risk control rules, but larger amounts typically require online authorization.
Conclusion
Walk through a Beijing subway gate or grab a bottle of water at a Chengdu convenience store and you will see the same silent action: a phone hovers over a reader for less than a second, and the exchange is done. What once looked like a novelty has become the default rhythm of urban life. This shift did not happen by accident. Years of coordinated investment turned millions of ordinary point-of-sale terminals into smart, contactless-ready devices, so even a tiny noodle shop can accept a tap as easily as a global chain. The result is a payment landscape where the phone has largely replaced the wallet, and where the line between online and offline commerce has blurred so completely that most people no longer think about the rails underneath.
Transport led the way. From metro turnstiles to buses to taxi rides, transit-first adoption gave commuters a daily reason to trust a tap, and that trust then spilled into cafes, markets, vending machines, and beyond. Security was designed to keep pace: tokenized credentials, device-bound keys, and risk engines that stay mostly invisible mean a payment clears quickly without asking the user to juggle passwords or sign receipts. The next wave pushes NFC further into civic life—building access, digital identity, hospital check-ins, and event entry all run through the same near-field handshake. China's contactless ecosystem is no longer just about paying; it is about moving through the city with a phone as a universal key.
Contact Us
Contact Person: Esme Mo
Email: [email protected]
Tel/WhatsApp: 0086 191 2931 7837
Website: https://www.osrfidglobal.com/